My Town Cryer
-
Join 750 other subscribers
-
Recent Blog Posts
What’s Tweetin’?
Tweets by MyTownCryerLinks That Help
- Centennial Real Estate
- Cherry Hills Village Real Estate
- Denver Market Data
- Denver Real Estate News
- Girls' Lacrosse in Vail Colorado
- Great Schools Search Site
- Greenwood Village Real Estate
- HUD Homes For Sale
- Inside Denver Real Estate
- Kentwood Company Items of Interest
- Luxury Home Short Sales
- Mortgage Interest Rates
- Moving to Denver?
- News from Colorado Springs
- Search Denver Real Estate
- The Town of Cherry Hills Village
- Trinity Property Inspection
- U.S. National Debt Clock
- World Champion Women's Lacrosse – Caroline Cryer
Archives
- November 2026
- September 2026
- August 2026
- July 2026
- June 2026
- May 2026
- April 2026
- March 2026
- February 2026
- January 2026
- December 2025
- November 2025
- October 2025
- September 2025
- August 2025
- July 2025
- June 2025
- May 2025
- April 2025
- March 2025
- February 2025
- January 2025
- December 2024
- November 2024
- October 2024
- September 2024
- August 2024
- July 2024
- June 2024
- May 2024
- April 2024
- March 2024
- February 2024
- January 2024
- December 2023
- November 2023
- October 2023
- September 2023
- August 2023
- July 2023
- June 2023
- May 2023
- April 2023
- March 2023
- February 2023
- January 2023
- December 2022
- November 2022
- October 2022
- September 2022
- August 2022
- July 2022
- June 2022
- May 2022
- April 2022
- March 2022
- February 2022
- January 2022
- December 2021
- November 2021
- October 2021
- September 2021
- August 2021
- July 2021
- June 2021
- May 2021
- April 2021
- March 2021
- February 2021
- January 2021
- December 2020
- November 2020
- October 2020
- September 2020
- August 2020
- July 2020
- June 2020
- May 2020
- April 2020
- March 2020
- February 2020
- January 2020
- December 2019
- November 2019
- October 2019
- September 2019
- August 2019
- July 2019
- June 2019
- May 2019
- April 2019
- March 2019
- February 2019
- January 2019
- December 2018
- November 2018
- October 2018
- September 2018
- August 2018
- July 2018
- June 2018
- May 2018
- April 2018
- March 2018
- February 2018
- January 2018
- December 2017
- November 2017
- October 2017
- January 2017
- April 2016
- July 2015
- June 2015
- April 2015
- February 2015
- January 2015
- December 2014
- November 2014
- October 2014
- August 2014
- July 2014
- June 2014
- April 2014
- March 2014
- February 2014
- January 2014
- December 2013
- November 2013
- October 2013
- September 2013
- August 2013
- July 2013
- June 2013
- May 2013
- April 2013
- March 2013
- February 2013
- January 2013
- December 2012
- November 2012
- October 2012
- September 2012
- August 2012
- July 2012
- May 2012
- April 2012
- March 2012
- February 2012
- January 2012
- December 2011
- November 2011
- October 2011
- September 2011
- August 2011
- July 2011
- June 2011
- May 2011
- April 2011
- March 2011
- February 2011
- January 2011
- December 2010
- November 2010
- October 2010
- September 2010
- August 2010
- July 2010
- June 2010
- May 2010
- April 2010
- March 2010
- February 2010
- January 2010
- December 2009
- November 2009
- October 2009
- September 2009
- August 2009
- July 2009
- June 2009
- May 2009
- April 2009
- March 2009
- December 2008
- November 2008
New Listing in Pradera
Posted in CASTLE ROCK, COUNTRY CLUB, GOLF COMMUNITY, PARKER, PRADERA
Leave a comment
Cryer says Shiller correct about mixed signals
“I truly believe, if we are nto at the bottom…the anchor is dragging along the bottom,” Cryer said. “It may bounce up or it may go deeper. But if you have the opportunity to be a buyer now, I could not imagine a better time to buy. We have historic low interest rates, and prices, in some respects, are where they were 10 years ago. And the credit markets have made it so tough to qualify for a loan, there is still not much competition for (the move-up and beyond) houses. It truly is a perfect storm for buying.”
http://insiderealestatenews.com/2009/08/cryer-says-shiller-correct-about-mixed-signals/
Out of the Box: Free at last!
“I’ll tell you what ticks me off,” Charlie grumbled, more than a little upset. “It’s all those folks in charge screwing us over! It’s like we were some kinda dummies for trustin’
’em and thinkin’ they had our best interests at heart!”
Well duh!
But the real reason Charlie’s mad is because all the scandals slapped him hard and forced him to wake up and smell the sewer.
They made him get real and tell himself the truth about what’s been going on for a very long time and they shattered his comfortable little illusions about the way the world works…
…and for that, Charlie hates them!
Because now he’s got to quit giving his power away to all those people and institutions he’s always trusted…and begin running his own life and trusting himself. You know, making his own calls, doing what *he* knows is best regardless of what “they” tell him.
Because “the screwin'” Charlie finally woke up and saw…is
true: most of the folks in charge really *don’t* care about you and haven’t for a long time. Money’s the name of the game, and their job’s to get as much of yours as they can…as fast as they can.
That’s why they screwed most everyone involved with Enron…
why stock analysts at major brokerage houses keep telling us to buy stocks they know are in the toilet…why Arthur Anderson got convicted…why WorldCom cooked the books…
…and it’s why Martha Stewart, the queen of K-Mart, allegedly, did a little insider trading.
All to pocket more of our money…which wasn’t hard because most of us make the huge mistake of trusting “them”…instead of trusting ourselves.
So this morning it’s time to change that. That’s right, it’s time to start trusting yourself and to tell the folks who’ve been running your life and controlling your wallet…including the corporations, churches, governments, friends and family who keep telling you “they” know what’s best for you…
…that it’s over!
And from now on you’ll be running your own life, thank you…
because “you” are the one you trust.
Sure, they’ll wail “You’re crazy!” and “Who do you think you are?” and “Have you lost your mind!?”. Yes, they’ll scream “I just want what’s best for you!” and they’ll tell you you’re going to fail, got to hell, lose your mind, get fired, go broke, and anything else they can think of to stop you.
Because if they don’t, you’ll be free…and they can’t stand the thought that you’ll no longer be under their control.
Today is *your* Independence Day! Take back your power and let the fireworks begin!
© Pat Lynch, 2002. All rights reserved.
Please feel free to forward this on.
***********
Out of the Box is a free weekly e-mail newsletter created to help you find more effective ways to release your potential and get the life you’ve always wanted.
New subscribers are welcome, and there is no charge. To subscribe, send an e-mail to: join-outofthebox@potential.com.
To unsubscribe, e-mail: leave-outofthebox@potential.com.
***********
Reproduction for publication is approved, provided the copyright information is included along with the following
attribution: From “Out of the Box”, a weekly newsletter by Pat Lynch. (602) 971-8525 or patlynch@potential.com.
***********
Got a story or experience that you think would be helpful to others in getting out of the box? Please send it to me
at patlynch@potential.com.
***********
Contact information:
Patrick Lynch
Potential Management
4757 E. Greenway Rd., Suite 107B, PMB 300 Phoenix, AZ 85032
E-mail: patlynch@potential.com
Phone: (602) 971-8525
Fax: (602) 971-8494
***********
For information on speaking, please e-mail me at patlynch@potential.com. You may also get more information
at: http://www.washspkrs.com/speaker.cfm/2265
Posted in Patrick Lynch
Leave a comment
FHA property flipping memo
June 8, 2006
MORTGAGEE LETTER 2006 -14
TO: ALL APPROVED MORTGAGEES
SUBJECT: Property Flipping Prohibition Amendment
On June 7, 2006, HUD published a final rule in the Federal Register amending regulations at 24 CFR 203.37a prohibiting property flipping in HUD’s single-family mortgage insurance programs by providing additional exceptions to the time restrictions on sales. The rule and this mortgagee letter become effective for mortgages endorsed for insurance on or after July 7, 2006. This Mortgagee Letter also rescinds, in their entirety, Mortgagee Letters 2003-07 and 2005-05.
The additional categories of properties exempted from the time restrictions include sales of properties by:
• State and Federally chartered financial Institutions and government-sponsored enterprises (GSEs) (e.g., Fannie Mae and Freddie Mac)
• Local and State government agencies
• Nonprofits approved to purchase HUD REO properties at a discount
http://www.hud.gov/offices/hsg/sfh/np/np_hoc.cfm
• Sales of properties within Presidentially-Declared Disaster Areas (upon FHA’s announcement of eligibility in a mortgagee letter specific to said disaster)
Prohibition on Property Flipping Described
Property flipping is a practice whereby a property is resold a short period of time after it is purchased by the seller for a considerable profit with an artificially inflated value, often abetted by a lender’s collusion with the appraiser. FHA’s policy prohibiting property flipping eliminates the most egregious examples of predatory flips of properties within the FHA mortgage insurance programs.
Overview of FHA’s Property Flipping Policy
FHA requires that: a) only owners of record may sell properties that will be financed using FHA-insured mortgages; b) any resale of a property may not occur 90 or fewer days from the last sale to be eligible for FHA financing; and c) that for resales that occur between 91 and 180 days where the new sales price exceeds the previous sales price by 100 percent or more, FHA will require additional documentation validating the property’s value. FHA also has flexibility to examine and require additional evidence of appraised value when properties are re-sold within 12 months.
Sale by Owner of Record
To be eligible for a mortgage insured by FHA, the property must be purchased from the owner of record and the transaction may not involve any sale or assignment of the sales contract. This requirement applies to all FHA purchase money mortgages regardless of the time between resales.
The mortgage lender must obtain documentation verifying that the seller is the owner of record and submit this to HUD as part of the insurance endorsement binder; it is to be placed behind the appraisal on the left side of the case binder. This documentation may include, but is not limited to, a property sales history report, a copy of the recorded deed from the seller, or other documentation such as a copy of a property tax bill, title commitment or binder, demonstrating the seller’s ownership of the property and the date it was acquired. Mortgagees participating in the Lender Insurance program (see ML 2005-36) are to retain this documentation and provide it to FHA upon request.
Resales Occurring 90 Days or Less Following Acquisition
If the owner sells a property within 90 days after the date of acquisition, that property is not eligible security for a mortgage insured by FHA unless it falls within one of the exceptions to the time restrictions on resales set forth in §203.37a(c) of the regulations. FHA defines the seller’s date of acquisition as the date of settlement on the seller’s purchase of that property. The resale date is the date of execution of the sales contract by the buyer that will result in a mortgage to be insured by FHA.
As an example, a property acquired by the seller is not eligible for a mortgage to be insured for the buyer unless the seller has owned that property for at least 90 days. The seller must also be the owner of record.
Resales Occurring Between 91 and 180 Days Following Acquisition
If the resale date is between 91 and 180 days following acquisition by the seller, the lender is required to obtain a second appraisal made by another appraiser if the resale price is 100 percent or more over the price paid by the seller when the property was acquired.
As an example, if a property is resold for $80,000 within six months of the seller’s acquisition of that property for $40,000, the mortgage lender must obtain a second independent appraisal supporting the $80,000 sales price. The mortgage lender may also provide documentation showing the costs and extent of rehabilitation that went into the property resulting in the increased value but must still obtain the second appraisal. The cost of the second appraisal may not be charged to the homebuyer.
FHA also reserves the right to revise the resale percentage level at which this second appraisal is required by publishing a notice in the Federal Register.
Resales Occurring Between 91 Days and 12 Months Following Acquisition
If the resale date is more than 90 days after the date of acquisition by the seller but before the end of the twelfth month following the date of acquisition, FHA reserves the right to require additional documentation from the lender to support the resale value if the resale price is 5 percent or greater than the lowest sales price of the property during the preceding 12 months. At FHA’s discretion, such documentation may include, but is not limited to, an appraisal from another appraiser.
FHA will announce its determination to require the additional appraisal and other value documentation, such as an automated valuation method (AVM), through a Federal Register issuance. This requirement may be established either nationwide or on a regional basis, at FHA’s discretion.
Exceptions to 90-day Restriction
The following sales are exempt from the time restrictions provided by §203.37a:
• Sales by HUD of its Real Estate Owned
• Sales by other United States Government agencies of single family properties pursuant to programs operated by these agencies.
• Sales of properties by nonprofits approved to purchase HUD-owned single-family properties at a discount with resale restrictions.
• Sales of properties that are acquired by the sellers by inheritance.
• Sales of properties purchased by employers or relocation agencies in connection with relocations of employees.
• Sales of properties by state and federally charted financial institutions and Government Sponsored Enterprises.
• Sales of properties by local and state government agencies.
• Upon FHA’s announcement of eligibility in a notice (i.e., ML), sales of properties located in areas designated by the President as federal disaster areas, will be exempt from the restrictions of the property-flipping rule. The notice will specify how long the exception will be in effect and the specific disaster area affected.
Inapplicability of §203.37a to New Construction
The restrictions in 203.37a are not applicable to a builder selling a newly built home or building a home for a homebuyer wishing to use FHA-insured financing.
Date of Property Acquisition Determined by the Appraiser
Mortgage lenders may rely on information provided by the appraiser in compliance with the updated Standard Rule 1-5 of the Uniform Standards of Professional Appraisal Practice (USPAP). This rule requires appraisers to analyze any prior sales of the subject property that occurred within
specific time periods, now set for the previous three years for one-to-four family residential properties.
As a result, the information contained on the Uniform Residential Appraisal Report or other applicable appraisal report form describing the Date, Price and Data for prior Sales is to include all transactions for the subject property within three years of the date of the appraisal and the comparable sales within 12 months of the date of the comparable sale. Appraisers are responsible for considering and analyzing any prior sales of the property being appraised within three years of the date of the appraisal and the comparables that are utilized within 12 months of the date of the comparable sale.
Therefore, provided that the URAR completed by the appraiser shows the most recent sale of the property to have occurred at least one year previously, no additional documentation is required from the mortgage lender. The mortgage lender remains accountable for verifying that the seller is the owner of record and may rely on information developed by the appraiser for this purpose if provided. However, if the lender obtains conflicting information before loan settlement, it must resolve the discrepancy and document the file accordingly.
If you have any questions regarding this Mortgagee Letter, please call 1-800-CALL-FHA.
– Sincerely,
Brian D. Montgomery
Assistant Secretary for Housing-
Federal Housing Commissioner
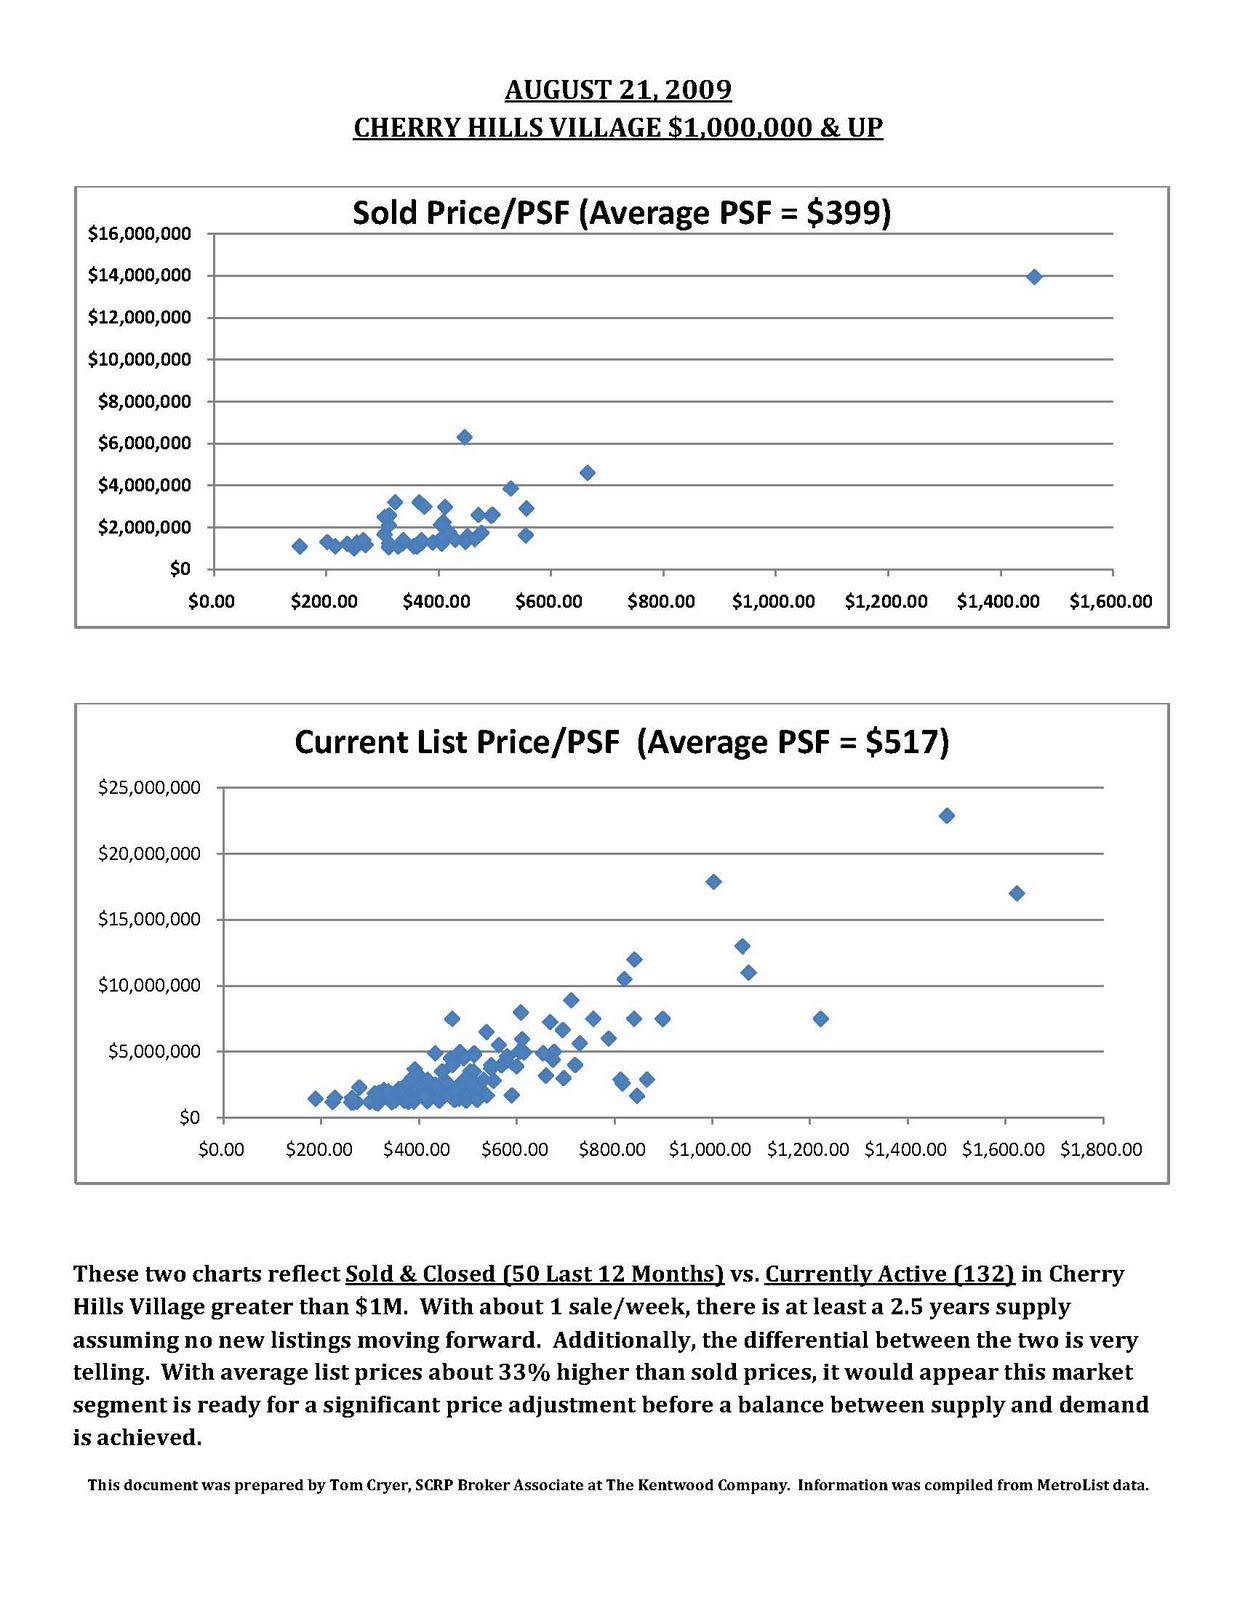
COMPARISON OF PRICE PER SQUARE FOOT SOLD VS. ACTIVING LISTED
AUGUST 21, 2009
CHERRY HILLS VILLAGE $1,000,000 & UP
These two charts reflect Sold & Closed (50 Last 12 Months) vs. Currently Active (132) in Cherry Hills Village greater than $1M. With about 1 sale/week, there is at least a 2.5 years supply assuming no new listings moving forward. Additionally, the differential between the two is very telling. With average list prices about 33% higher than sold prices, it would appear this market segment is ready for a significant price adjustment before a balance between supply and demand is achieved.
This document was prepared by Tom Cryer, SCRP Broker Associate at The Kentwood Company. Information was compiled from MetroList data.
Posted in Uncategorized
Leave a comment
Did you ever consider this? Average price is simple;
Did you ever consider this? Average price is simple; add up all the sales prices divide by the number of transactions – voila’; there’s your number. But what really goes into this average price?
Over the years, houses have become larger. The average size of houses has increased. I think this is the first year in my lifetime where the average size of a new house actually dropped. But, beyond that, houses have more STUFF; electronics, garage openers, microwaves, more bathrooms, basements have higher ceilings, closets are bigger, alarms here and there, wood, slate, granite, marble, etc.
Are you still following me? Here we go, have homes appreciated as much as we think they have based on reported average prices, or have houses become larger, more content rich and more functional over time as to give us a perception of appreciation than might actually be occurring from cost rather than market driven forces.
I know this topic is a little esoteric, but the average price of a house in its 1950s version is significantly different than the average price of a house in 1980s trim, and so on. Are we comparing apples to apples – year after year?
Posted in एवरेज होम प्रिक्स...
1 Comment
It is 2:49 PM in Denver righ now. It is raining cats and dogs in the Tech Center!
Posted in Uncategorized
Leave a comment
The Streets at SouthGlenn Announces Colorado Grand Opening
One of Nation’s only Mixed-Use Centers to Open in Centennial, CO on August 28, 2009
CENTENNIAL, CO. August, 25 2009 – On Friday, August 28, The Streets at SouthGlenn, one of the country’s only large scale, mixed-use projects to open this year, will celebrate its grand opening festivities with the public. This three day celebration marks the completion of a historic project and sets a new benchmark for collaborative re-development. All weekend long, shoppers can experience “life on The Streets” exploring new retailers and restaurants while interacting with entertainers including stilt walkers, jugglers, human statues, face painters, balloon artists and musical acts.
“The Grand Opening of The Streets at SouthGlenn is monumental for not only the area but the shopping center industry. In a time where shopping center openings are delayed indefinitely, we are extremely proud to bring The Streets at SouthGlenn to Centennial and south Denver,” said Don Provost, principal of Alberta Development Partners. “Our vision has always been to bring urban character and charm to an area where people can gather for shopping, dining, entertainment and outdoor community events. We are finally about to bring that vision to a reality.”
The Streets at SouthGlenn is a $310 million, 77 acre infill project where the developers razed the previous 1972 era Southglenn Mall to make way for the new mixed-use center. Comprised of 1.2 million square feet of retail, 140,000 square feet of Silver LEED certified, Class A office space, and 202 luxury apartments, the project combines national retail shops, local boutiques, restaurants, a health club and entertainment options in a completely unique outdoor setting. The Streets at SouthGlenn is also home to the Commons, a classic, urban park, with a grand European fountain, antique brick fireplace, 30 feet tall legacy trees, lush gardens and outdoor cafés.
The entire community is invited to celebrate a weekend full of activities starting Friday at 9:00 a.m. with a ribbon cutting ceremony. Shoppers can enjoy food and entertainment as they experience South Denver’s newest shopping destination. The Streets at SouthGlenn is the newest project to come online from area developer, Alberta Development Partners, LLC. Alberta Development Partners has deep Colorado roots with previous mall openings including Southlands and Cornerstar both in Aurora, CO.
The grand opening of the 1.5 million square foot shopping destination will include an 18,000 square foot Arapahoe Public Library, flagship Whole Foods, Grapes Wine and Liquor, Best Buy, Dick’s Sporting Goods, Bar Louie, Mellow Mushroom, Chrysallis, Kismet, Color Me Mine, The Oven, Salon AKA, 720 Board Shop, Diego Zhang’s, Larry Johnson Gallery, Bouquets and many more. Hollywood Theaters, a 14 screen with reserved seating theater, will open this fall along with more retailers and restaurants and 24 Hour Fitness, a 48,000 square foot Super Sport, will be debuting this winter. The Portola at SouthGlenn, a 202 unit luxury rental community at the location, includes five elegant and contemporary floor plans ranging from 560 SF to 1834 SF.
Located at the crossroads of University Boulevard and Arapahoe Road, The Streets at SouthGlenn, 6851 S. Gaylord Street, is minutes away from C470 and I-25 and is the ideal location to live, work or play.
In addition to the ribbon cutting at 9:00 a.m. on Friday August 28th, festivities for The Streets at SouthGlenn will include in-store promotions, radio remotes, entertainment, giveaways and food for all shoppers, as well as a movie night. On Saturday, August 29th the action continues at 10:00 a.m. and runs through 5:00 p.m. with entertainment and giveaways and a live concert in the park. The grand opening celebration concludes on Sunday, August 30th from 10:00 a.m. until 5:00 p.m. with more food, giveaways and entertainment for everyone!
For more information on The Streets at SouthGlenn and the grand opening festivities along with a complete listing of retailers and restaurants, visit http://www.shopsouthglenn.com or call 303-771-4004.
*************************
Arapahoe County seeking citizens to serve on the Cultural Council
The Arapahoe County Board of County Commissioners has openings on the Cultural Council and is seeking applications from residents who are interested in helping their community. There are two openings for an Aurora representative, one opening for a Centennial representative and one opening for an Englewood, Littleton and Sheridan representative. Qualified applicants must be residents of Arapahoe County and must reside in one of these areas to apply for these positions.
The Cultural Council considers which nonprofit organizations and government entities in the county will receive its share of money from the metro-wide Scientific and Cultural Facilities District sales tax. Note from Andrea: This is the money distributed from the Colorado lottery.
The application deadline is Sept. 4, 2009. Interested residents can apply online. To fill out an online application, visit the County’s web site at http://www.co.arapahoe.co.us and click on online tools. Applications also are available at the Commissioners Office in the County Administration Building, 5334 S. Prince St., Fourth Floor, Littleton.
For more information on a particular board or to request an application by mail, call Carol Dosmann at the Commissioners Office at 303-795-4531.


You must be logged in to post a comment.